A company that needs capital usually starts with a number. Twenty million dollars to build a plant. Fifty million to buy a competitor. The number feels like the hard part.
It rarely is. The harder question is whose capital it should be.
Two investors can offer the same amount on terms that lead to two very different companies five years later. One expects a board seat and a sale within its fund’s life. Another wants a supply agreement and no exit at all. A third will lend, ask for covenants, and never attend a board meeting.
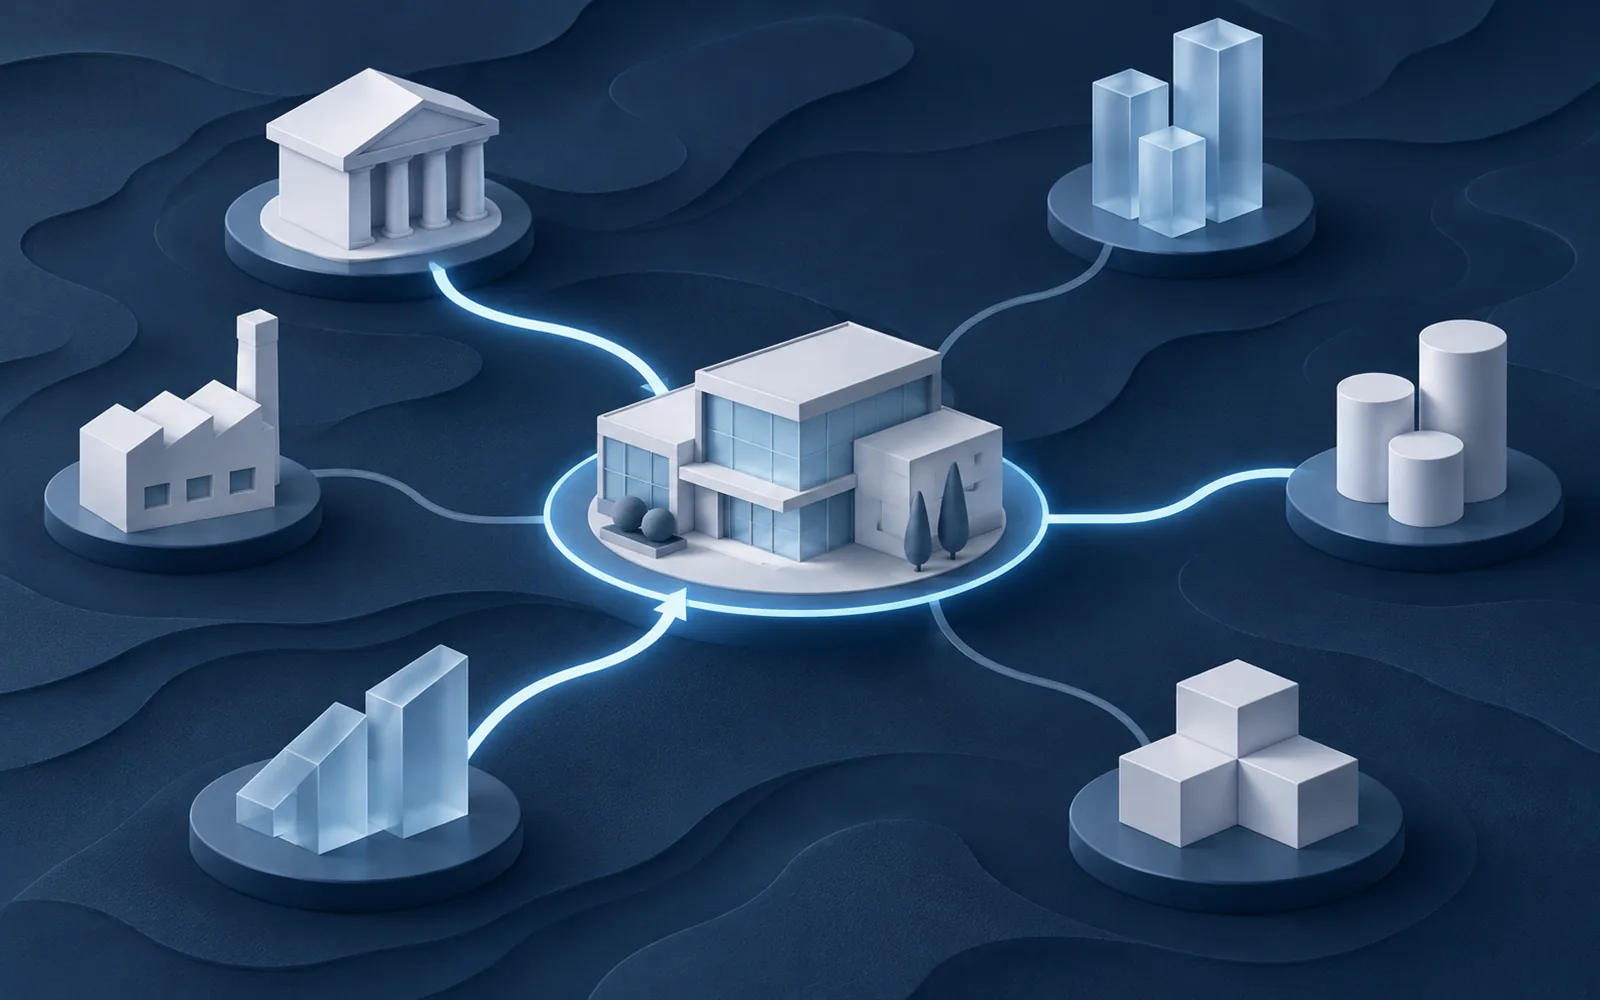
Capital placement begins with fit, not volume. Fit begins with knowing who is on the map, and what each of them is trying to accomplish with the money.
Strategic investors: capital with an operating agenda
A strategic investor is an operating company, often a larger one in the same industry or an adjacent one. It invests to advance its own business. It may want access to a product, a region, a technology or a supply source.
That agenda cuts both ways. A strategic can bring customers, distribution and credibility that no financial investor can. It can also bring conditions: exclusivity, a right of first offer, or influence over who the company may sell to later.
The useful question is not whether the strategic values the company. It is what the strategic is buying besides equity.
Institutional investors: capital on a clock
Private equity firms, growth investors and private credit funds manage money on behalf of others. Most raise funds with a defined life, and that life sets a clock. Capital goes in during the early years and is expected back, with a return, before the fund ends.
The clock explains much of how these investors behave. It is why they ask about the exit at the first meeting. It is why governance terms, reporting requirements and rights around a future sale appear in the first draft of a term sheet.
None of this is a drawback in itself. An owner who also wants a sale in five years may find the clock helpful. An owner who wants to hold for twenty will not.
The amount is a number. The investor is a partner.
Specialized funds: capital with a written mandate
Some funds exist to do one thing. They invest only in infrastructure, or energy, or food and agriculture, or a single type of real estate. Others are defined by instrument, such as mezzanine debt or preferred equity.
A specialized fund’s mandate is written down, and its managers are bound by it. That makes these investors efficient to work with when the fit is exact. They know the sector, they ask informed questions and they can price risk that a generalist would decline.
It also makes them a poor use of time when the fit is close but not exact. A fund that cannot hold a minority position will not make an exception for a good company.
A fund’s mandate tells you more than its size.
Family offices: capital with private rules
A family office invests the wealth of one family or a small number of families. It answers to no outside investors, so it sets its own rules. Many can hold an investment far longer than a fund can. Some will take structures that institutions avoid.
The same independence makes family offices hard to generalize about. One decides in three weeks through a single principal. Another runs a committee process as formal as any institution’s. Interests often follow the business in which the family made its money.
The work with a family office is learning its particular rules early: who decides, what they have done before, and what they have said no to.
Sovereign and offshore capital: long horizons, long processes
Sovereign wealth funds invest on behalf of governments. Offshore investors, including foreign companies, families and funds, invest across borders for diversification, strategic access or both. Many think in decades.
Long horizons come with long processes. Decision chains can run through several layers and more than one country. Diligence expectations are high. Cross-border investments may also involve regulatory review, tax structuring and currency questions that a domestic investment would not.
For the right company and the right project, this capital is patient and substantial. It is seldom fast.
What the map is for
The map does not pick the investor. It narrows the field before anyone is called. Three questions do most of the narrowing:
- What must the capital do? Fund growth, buy out a partner, refinance debt and finance an acquisition each point to different sources.
- What can the company give? Control, board seats, information rights, commercial terms and a future exit are all forms of payment.
- How long can the capital stay? The company’s own timeline should match the investor’s, not fight it.
A company that answers these three before approaching the market will speak with fewer investors. More of those conversations will be worth having.
Your next step
Write down the answers to the three questions above before any outreach begins. Where the answers conflict, such as wanting patient capital and a fast close, settle the priority first. Investors will ask.
The next piece in this series covers how a targeted investor list is built, and why a short list tends to outperform a long one.
This article is general information. It is not investment, legal or tax advice, and it is not an offer to buy or sell any security.
Securities are offered through GT Securities, Inc. | Member FINRA, SIPC